Working Capital & Cash Flow
CC, OD, WCDL, invoice finance, TReDS and blended structures based on the real operating cycle.
IMFL helps Indian business owners understand the real requirement, structure funding around cash flow, prepare a lender-ready credit case and stay sharper after sanction. Working capital, MSME finance, machinery, project expansion, debt reset, CGTMSE and GCC/vendor funding - with human handholding and consultant-led thinking.
Clear, practical and human-friendly advisory built around what real owners face on the ground.
Strong and highly qualified credit analyst team supporting fitment, note-making and lender-ready case building.
Connectivity across major public-sector and private-sector banks, NBFCs and execution channels.
IMFL advises on optimum utilisation of funds so the business can grow capital-rich without unnecessary pressure.
Business owners usually know they need funds. What they need more urgently is clarity - how much, for what, from where, in what structure and how to use it without choking the business later.
Working capital, receivable finance, machinery, project debt and promoter contribution are assessed separately so the funding structure reflects business reality.
Every bank and NBFC has a different appetite. IMFL matches the profile to suitable lenders before a case is pushed into the market.
Capital is useful only when utilisation is controlled. IMFL supports cleaner deployment, renewal readiness and better future fundability.
Not a generic loan listing experience. IMFL helps build the funding case, fit the lender, present the business properly and advise on the use of funds.
CC, OD, WCDL, invoice finance, TReDS and blended structures based on the real operating cycle.
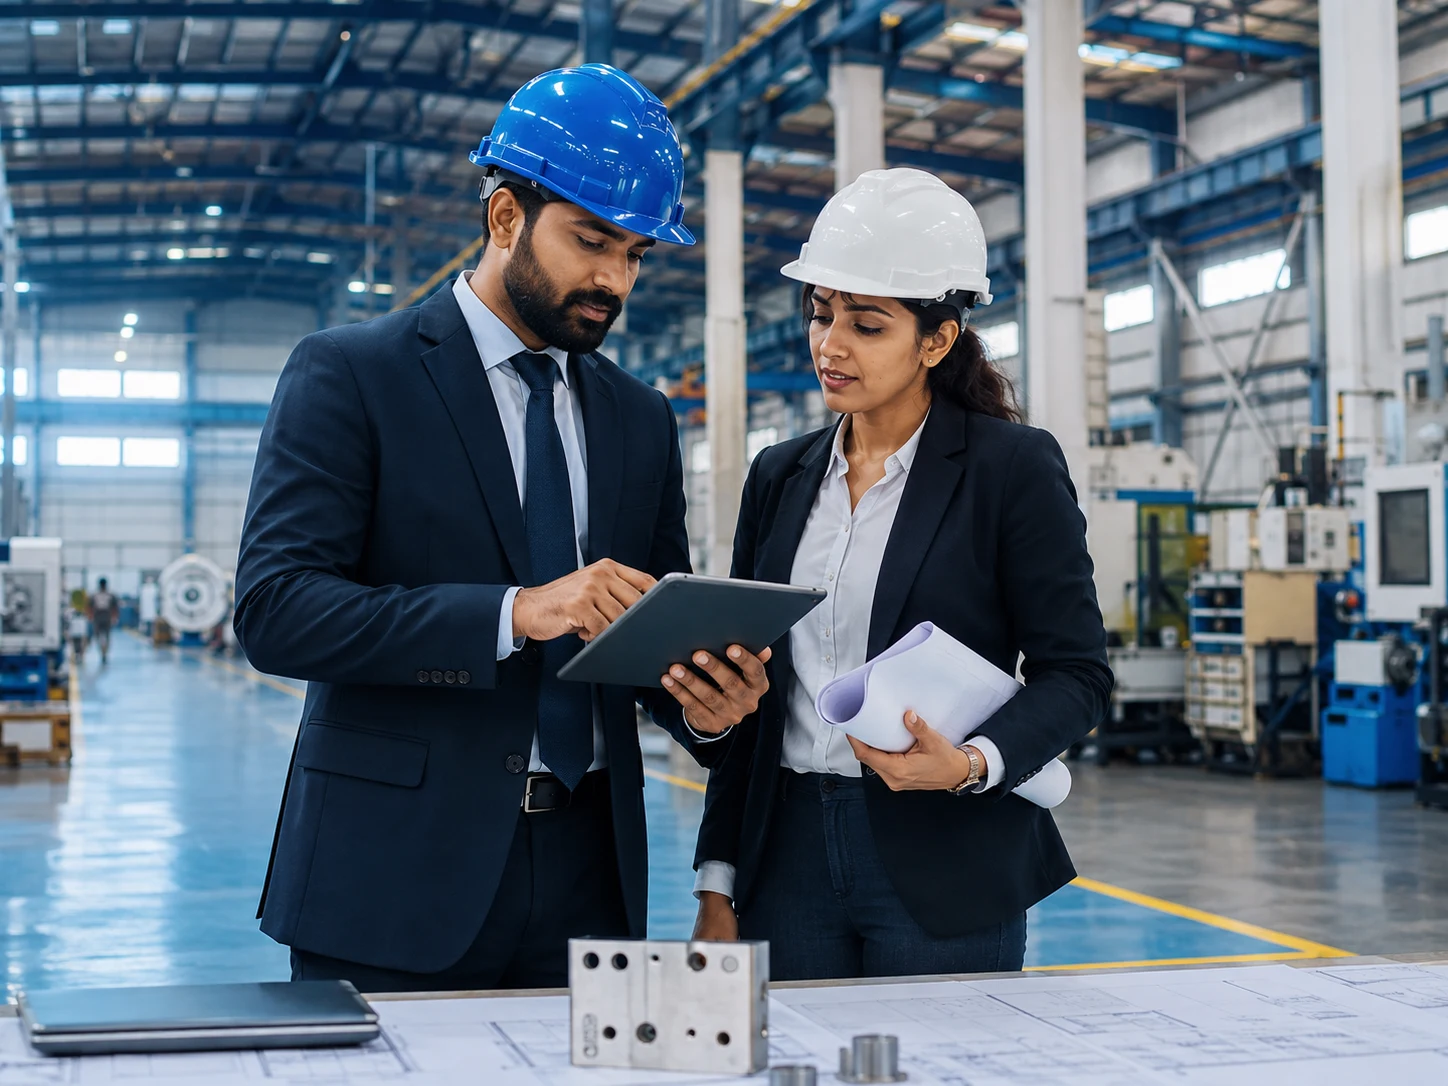
Factory expansion, equipment purchase, automation and capex funding structured around projected cash accrual.
Review existing EMI pressure, enhancement, consolidation, takeover and capital rebalancing opportunities.
Turn large corporate orders into executable growth with supplier finance, invoice discounting and contract-linked liquidity.
Consulting-led MSME funding support built around business model, cash flow quality and lender-policy fit.
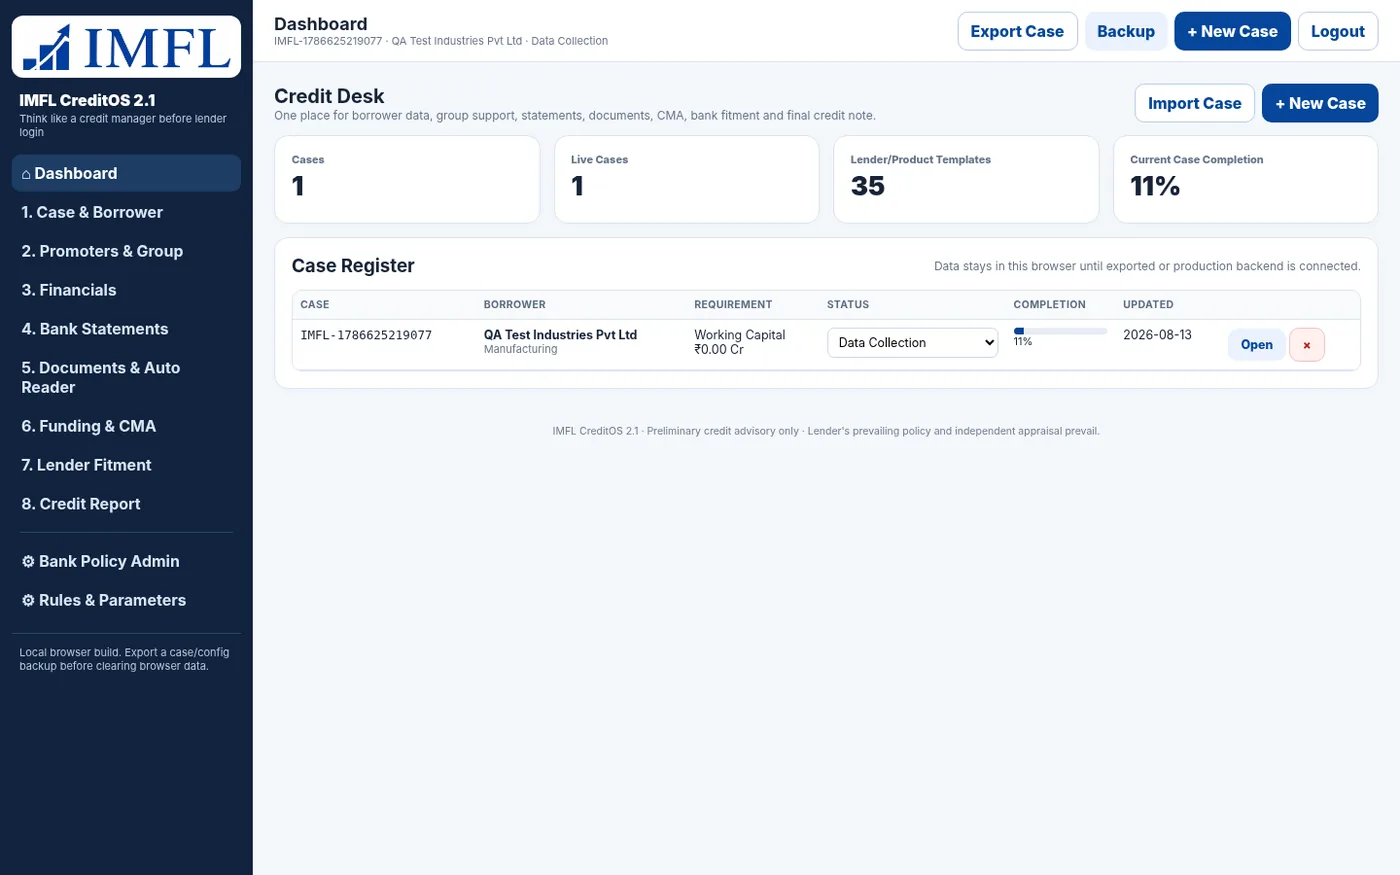
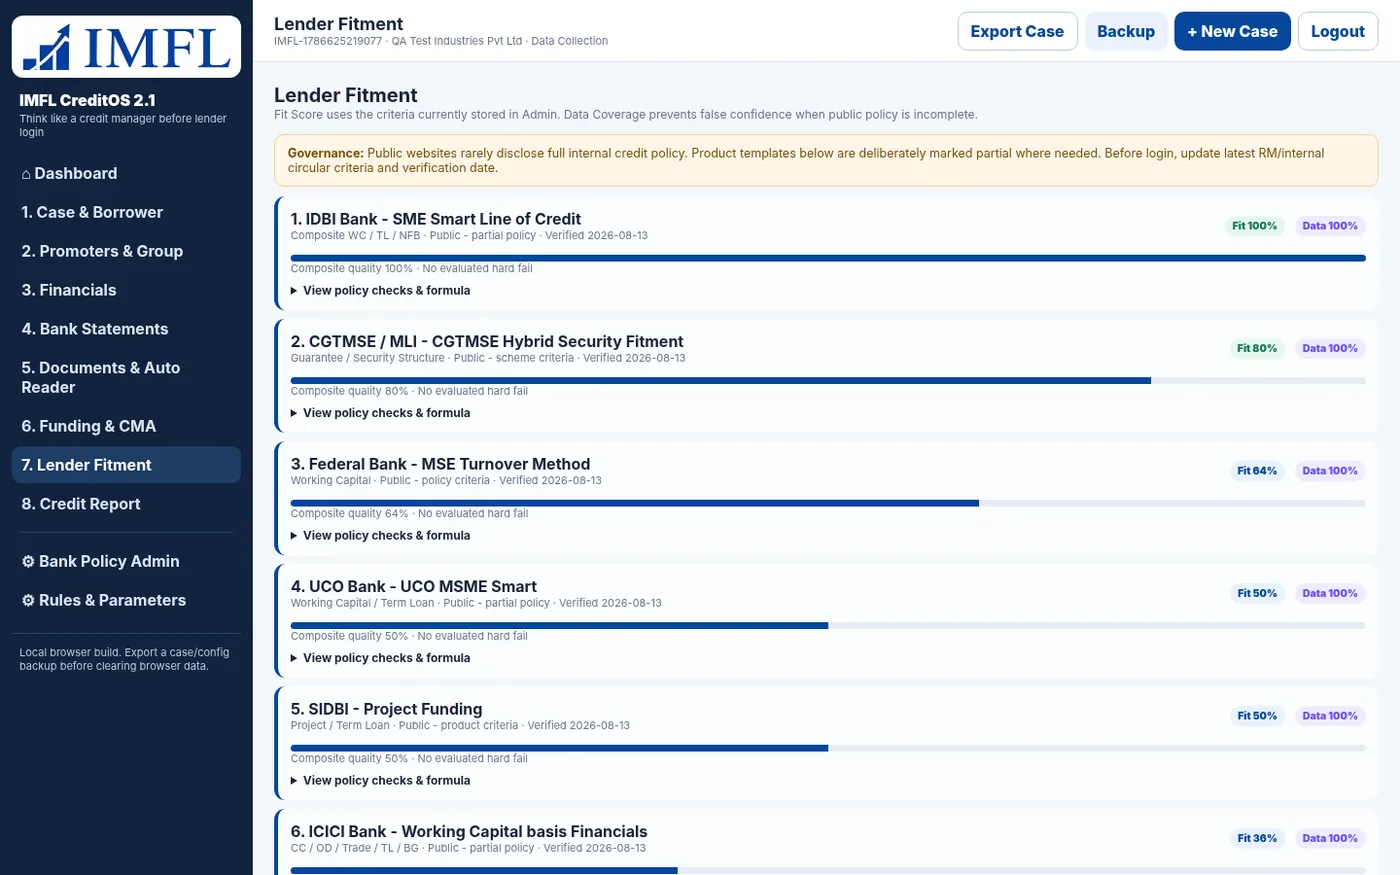
CMA view, fitment note, case narrative, document discipline and a cleaner report flow for lender discussions.
IMFL CreditOS supports multiple bank-statement reading, financial-document review, ratio analysis, lender fitment, deviations and structured reporting so the business can be presented more clearly.
IMFL’s direction is shaped by professionals who understand lending, distribution, execution and service quality - with a practical focus on handholding Indian business owners through capital decisions.
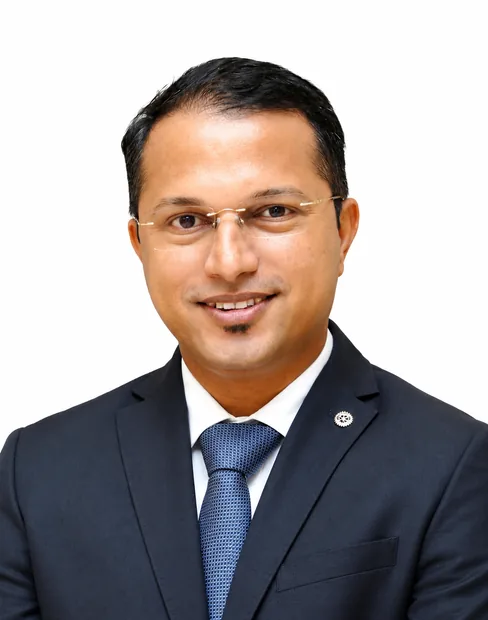
15+ years of experience across HDFC Sales and Bajaj Housing Finance, backed by executive learning at IIM Ahmedabad. Santosh brings systems thinking, service-sector understanding, advisory orientation and a deep focus on building a cleaner, smarter and more useful funding experience for business owners.
His leadership lens strengthens IMFL’s positioning not only as a funding support partner, but as a financial/business consultant for optimum utilisation of funds.
IMFL is also supported by a strong and highly qualified credit analyst team with execution exposure, banking-connect understanding and lender-facing report capability.
These are common situations where a business may look “fine” from the outside, but still needs better capital thinking, stronger financial control and external credit guidance.
Many businesses confuse growth with liquidity. More orders can actually increase pressure when receivables stretch, inventory rises and the old capital structure stays unchanged. IMFL helps owners see where cash is getting absorbed before the stress becomes visible in the bank account.
A capable finance team can maintain books, GST, MIS and compliance - but funding decisions also depend on bank policy, credit appetite, structuring logic, collateral strategy and how the business story is presented. That needs a consultant view, not just an internal control view.
Working capital, machinery, project debt, receivable finance and debt restructuring solve different business situations. When everything is pushed into one product, the business often carries the wrong EMI burden or the wrong repayment pattern. IMFL focuses on optimum utilisation of funds, not funding for its own sake.
The right answers usually sit between business reality, lender policy and timing. Here are the questions IMFL hears most often.
The right route depends on your operating cycle, GST turnover, banking conduct, receivable days, inventory pattern and existing limits. IMFL reviews the real cash cycle first and then evaluates options such as CC, OD, WCDL, invoice finance, TReDS or a blended structure.
Profit and cash are not the same. Money can remain stuck in receivables, inventory, WIP, margin requirements, old EMIs or uneven repayment dates. IMFL helps business owners see where cash is actually getting blocked before adding more debt.
A business loan can still be rejected because of lender-policy mismatch, weak banking conduct, GST and financial mismatches, low cash accrual, leverage, incomplete documents, poor bureau, unsupported projections or simply the wrong facility structure.
In suitable cases, yes. Eligible businesses may access collateral-light or guarantee-backed structures such as CGTMSE through participating lenders, subject to prevailing rules and the lender’s policy. IMFL checks whether unsecured, hybrid-security or secured funding is the better fit.
Usually lenders expect KYC, PAN, GST, Udyam, audited or provisional financials, ITR, bank statements, sanction letters, debtor and creditor ageing, stock details and project or machinery information. Clean, reconciled documents reduce avoidable back-and-forth.
There is no universal best bank. The right lender depends on sector, ticket size, collateral, profitability, banking conduct, existing exposure, geography, facility type and current policy appetite. IMFL helps shortlist lenders after seeing the full business picture.
A CMA report converts business numbers into a lender-readable credit view. It helps the bank assess working-capital need, profitability, leverage, liquidity and repayment ability. IMFL treats CMA as a business story backed by numbers, not just a format to be filled.
Yes. Many businesses need a capital-structure review before they need another loan. IMFL can review existing CC, OD, term loans, LAP, unsecured debt and repayment dates together to evaluate enhancement, consolidation, refinancing or restructuring options.
Yes, subject to viability and lender policy. IMFL can help evaluate machinery finance, project finance, factory expansion funding, order-backed working capital, receivable finance and vendor-related structures around the actual execution timeline.
Yes. IMFL provides PAN-India advisory for business funding and capital structuring. The first review can start digitally as soon as the basic business details and initial documents are shared.
No lamba application form. Share the basics and the IMFL team will guide the next smart step for a proper funding review.